What is an FHA mortgage?
An FHA mortgage is a home loan insured by the Federal Housing Administration. Because the government backs part of the loan, down payment and credit requirements are more flexible than many conventional loans. In exchange, FHA loans require paying for mortgage insurance, both upfront and monthly. You can choose a fixed rate or an adjustable rate on an FHA loan.

Who are FHA home loans for?
First-time buyers
An FHA home loan is a common first step for first-time buyers. It requires less money down, and gift funds can help cover it.
Buyers without savings for a large down payment
If saving for a larger down payment would delay your homebuying plans, an FHA loan may help you get into a home sooner with a lower down payment requirement.
Anyone building their credit
FHA guidelines are more flexible on credit scores and past credit events, so a lower score doesn't automatically rule you out.

More FHA financing options
FHA financing goes beyond home purchases, with options available for renovations, new construction, and refinancing.


FHA loan benefits and requirements
See what an FHA loan can do, and what it asks of you, before you talk numbers.
A smaller down payment
FHA loans may require less money down than many conventional loan programs, and eligible gift funds can be used for the down payment.
More room on income and credit
FHA guidelines are more flexible on income and credit than many conventional loans, so a lower score or a past credit event doesn't automatically rule you out.
Open to repeat buyers
FHA loans aren't just for first-time homebuyers. You may be able to use FHA financing again when purchasing a new primary residence.
A home you'll live in
FHA loans are for your primary residence. That can be a house, an approved condo, or a 1- to 4-unit property where you live in one unit.
Steady income, with flexible guidelines
You'll show reliable income and meet FHA's credit guidelines, which leave more room than many conventional loans. Your loan officer can tell you where you stand in one conversation.
A smaller down payment, plus mortgage insurance
You'll need a down payment, but it can be smaller than many conventional loans and can come from gift money. In exchange, every FHA loan carries mortgage insurance, paid upfront and monthly.
Compare side by side
FHA vs conventional
Which is the better fit depends on your eligibility, your savings, and your plans.
Conventional loans
Often a fit for buyers with stronger credit and more saved.
Down payment
- Usually more up front
Credit flexibility
- Works best with strong credit
Mortgage insurance
- Can be removed once you've built enough equity
FHA loans
Built for buyers with less saved or credit that's still taking shape.
Down payment
- Smaller down payment options
Credit flexibility
- More flexible on income and credit
Mortgage insurance
- Upfront and monthly; often lasts until you refinance
Tools & Calculators
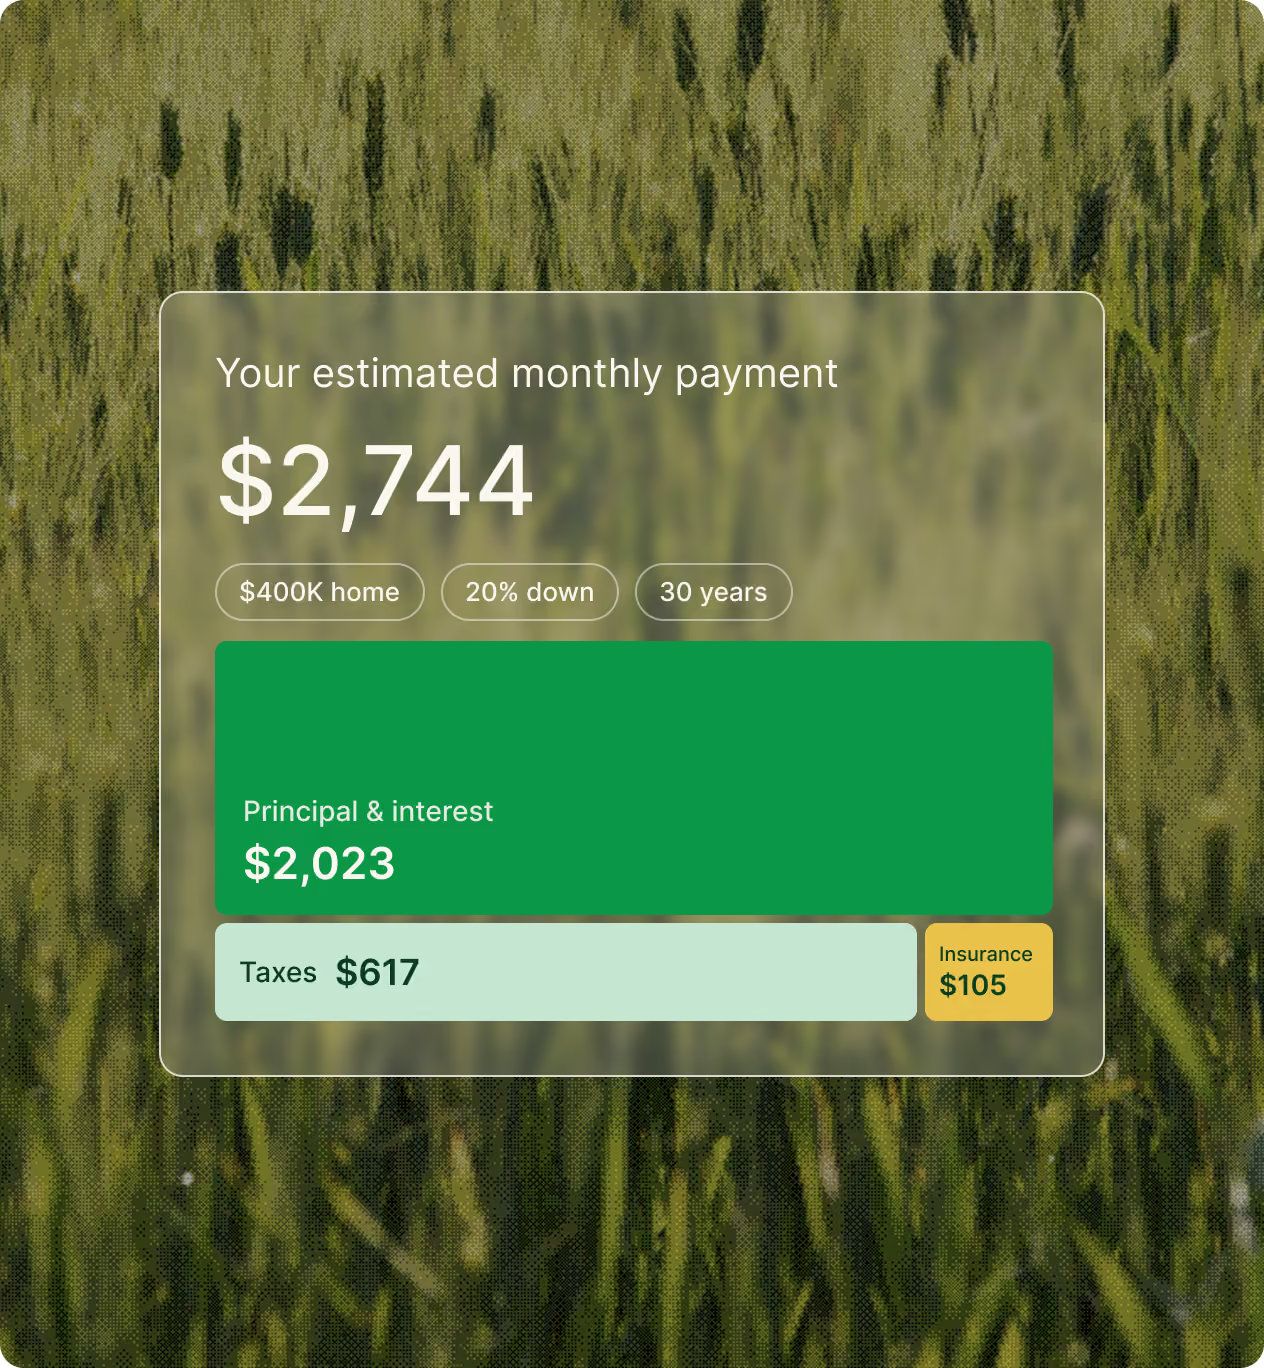
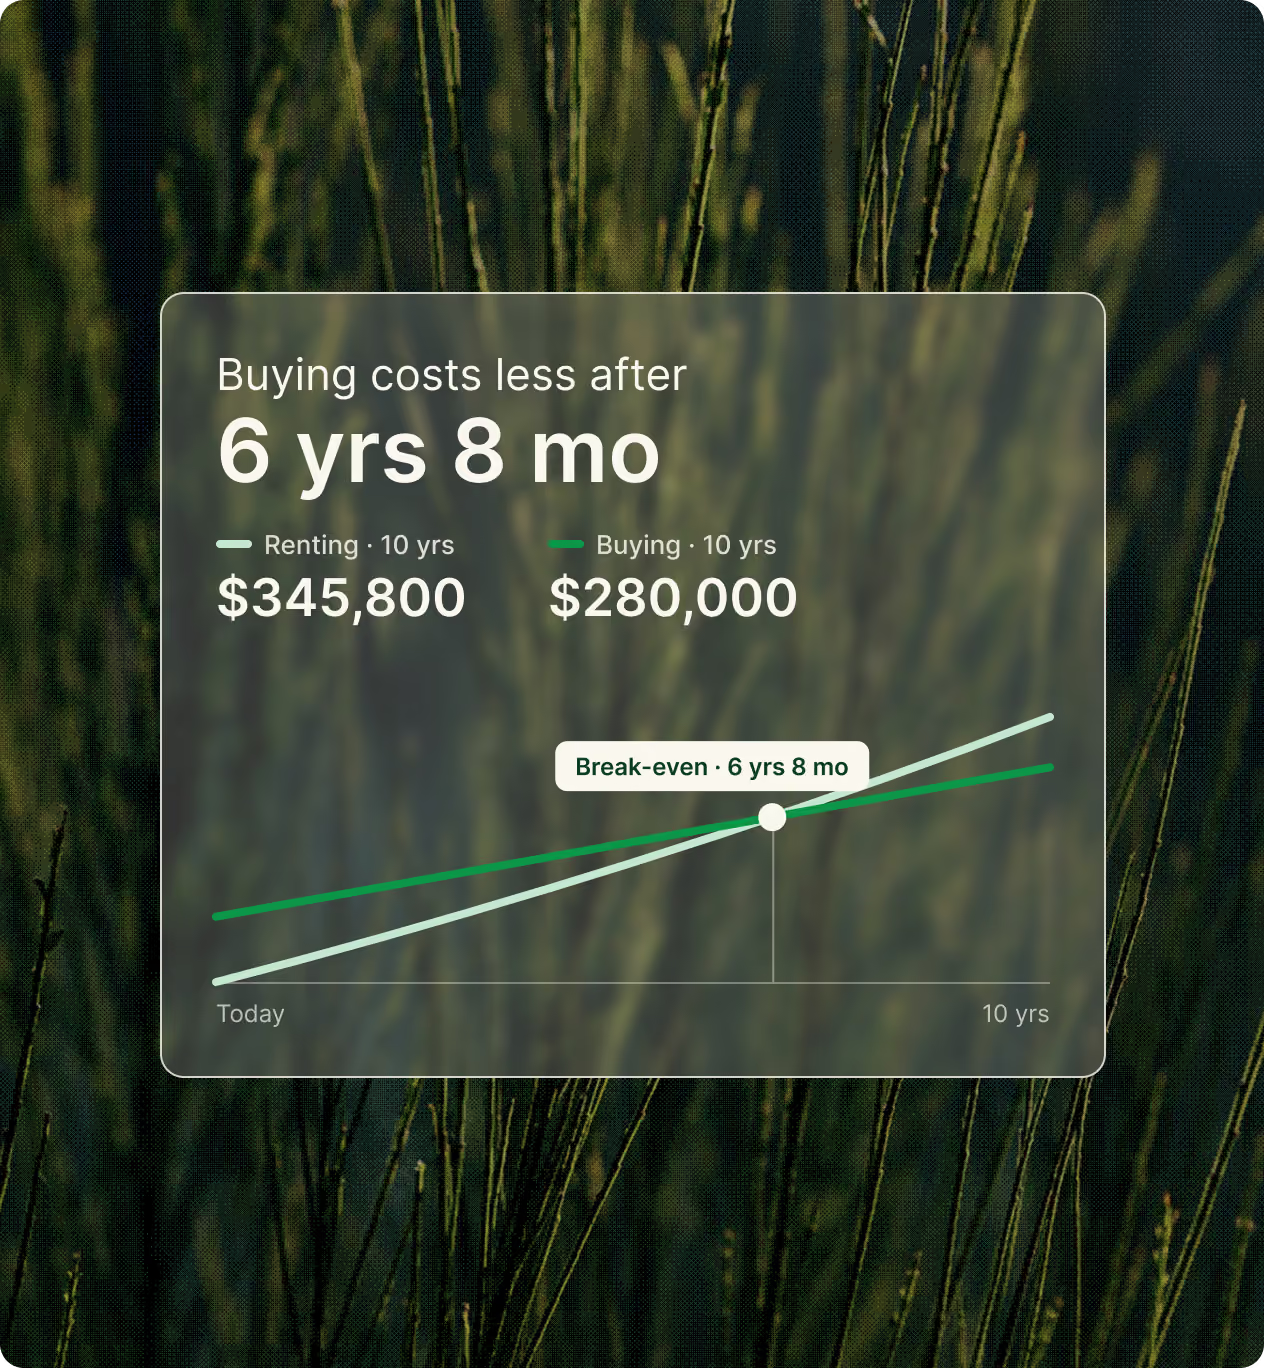
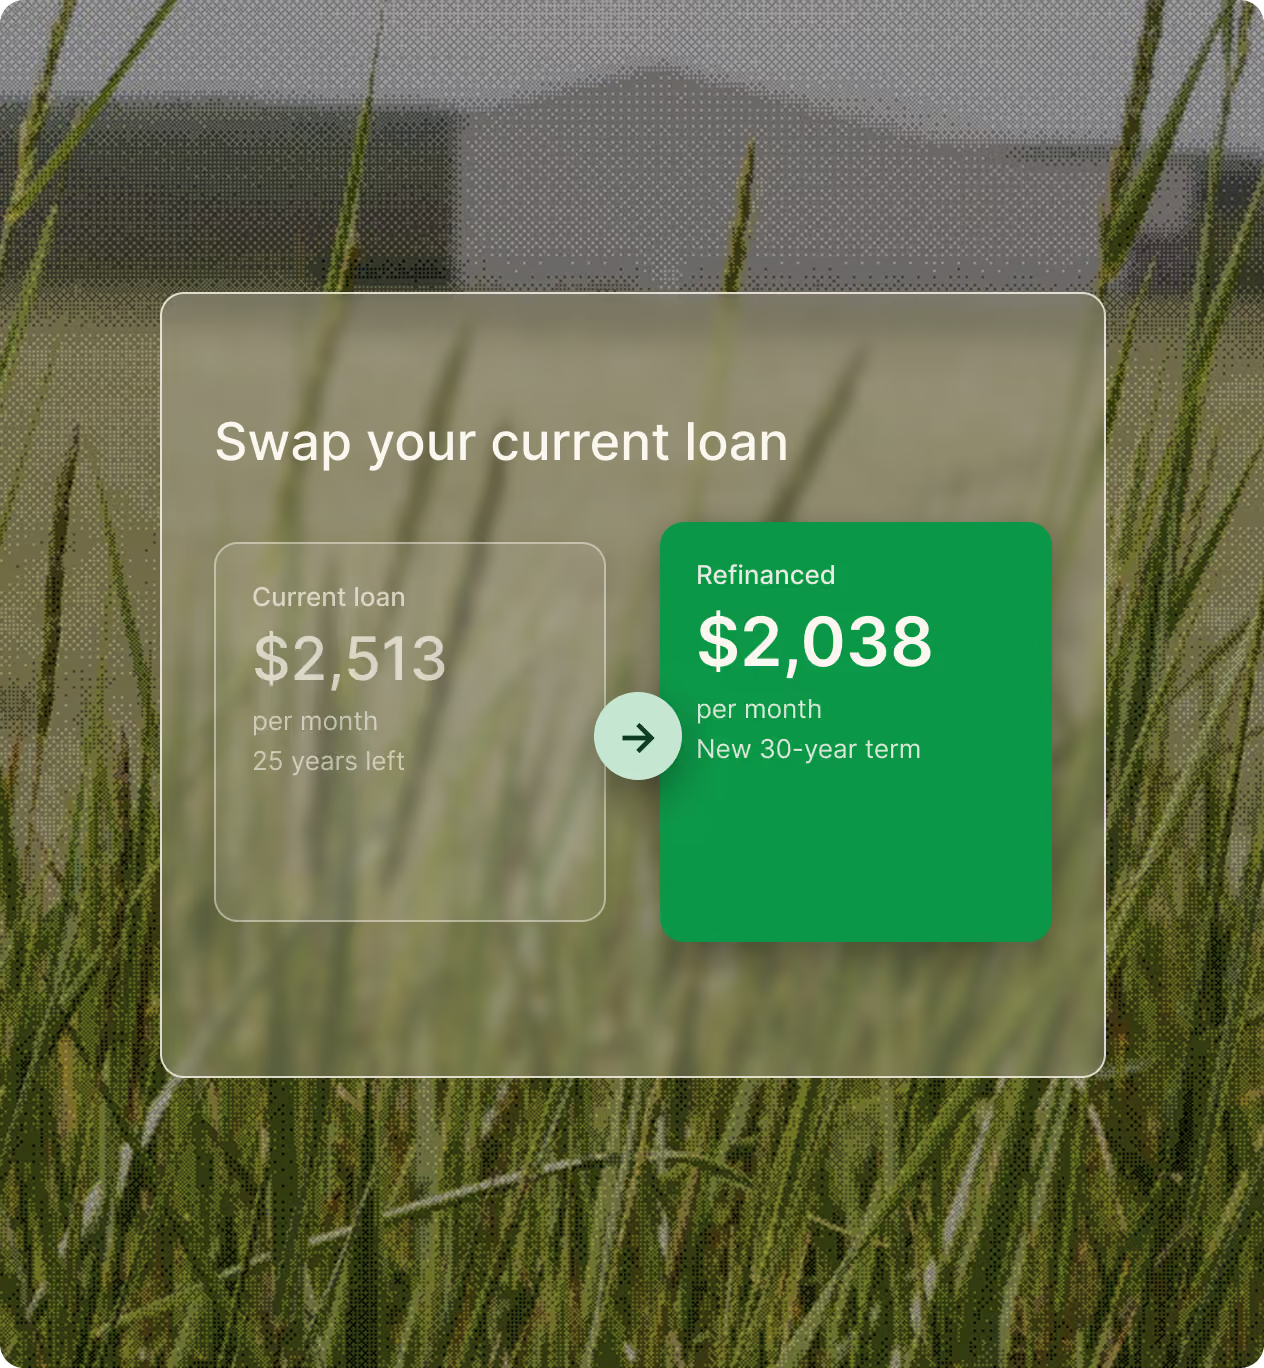
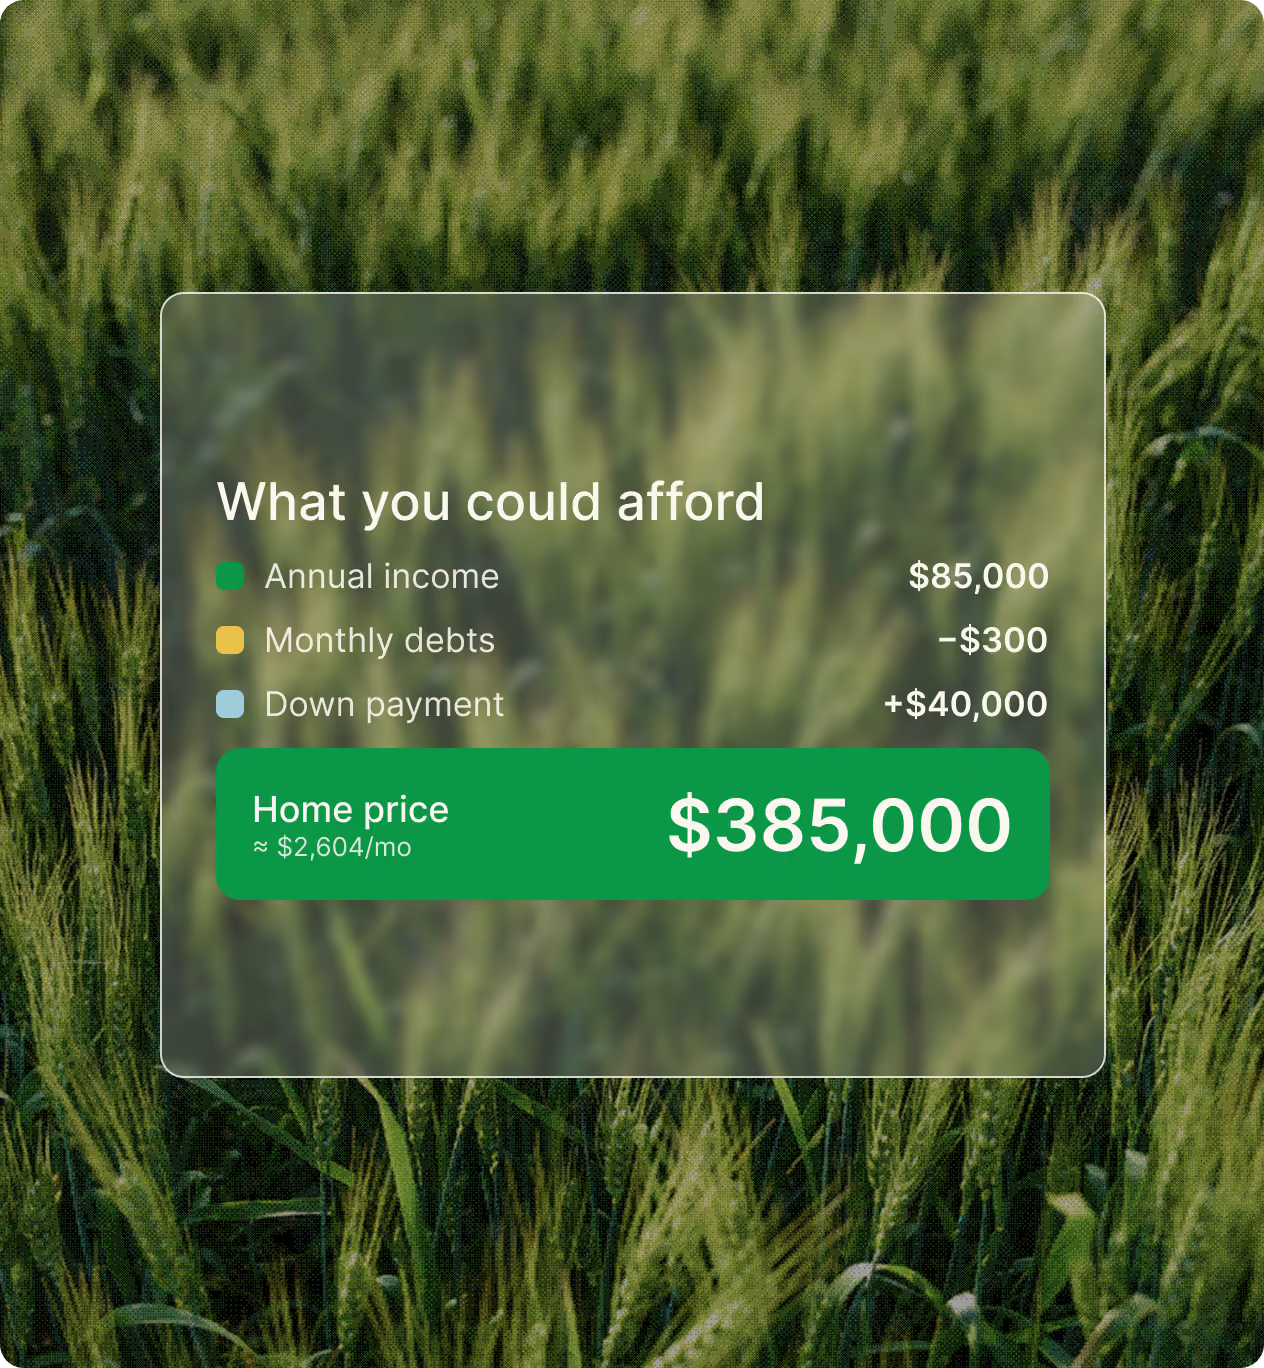
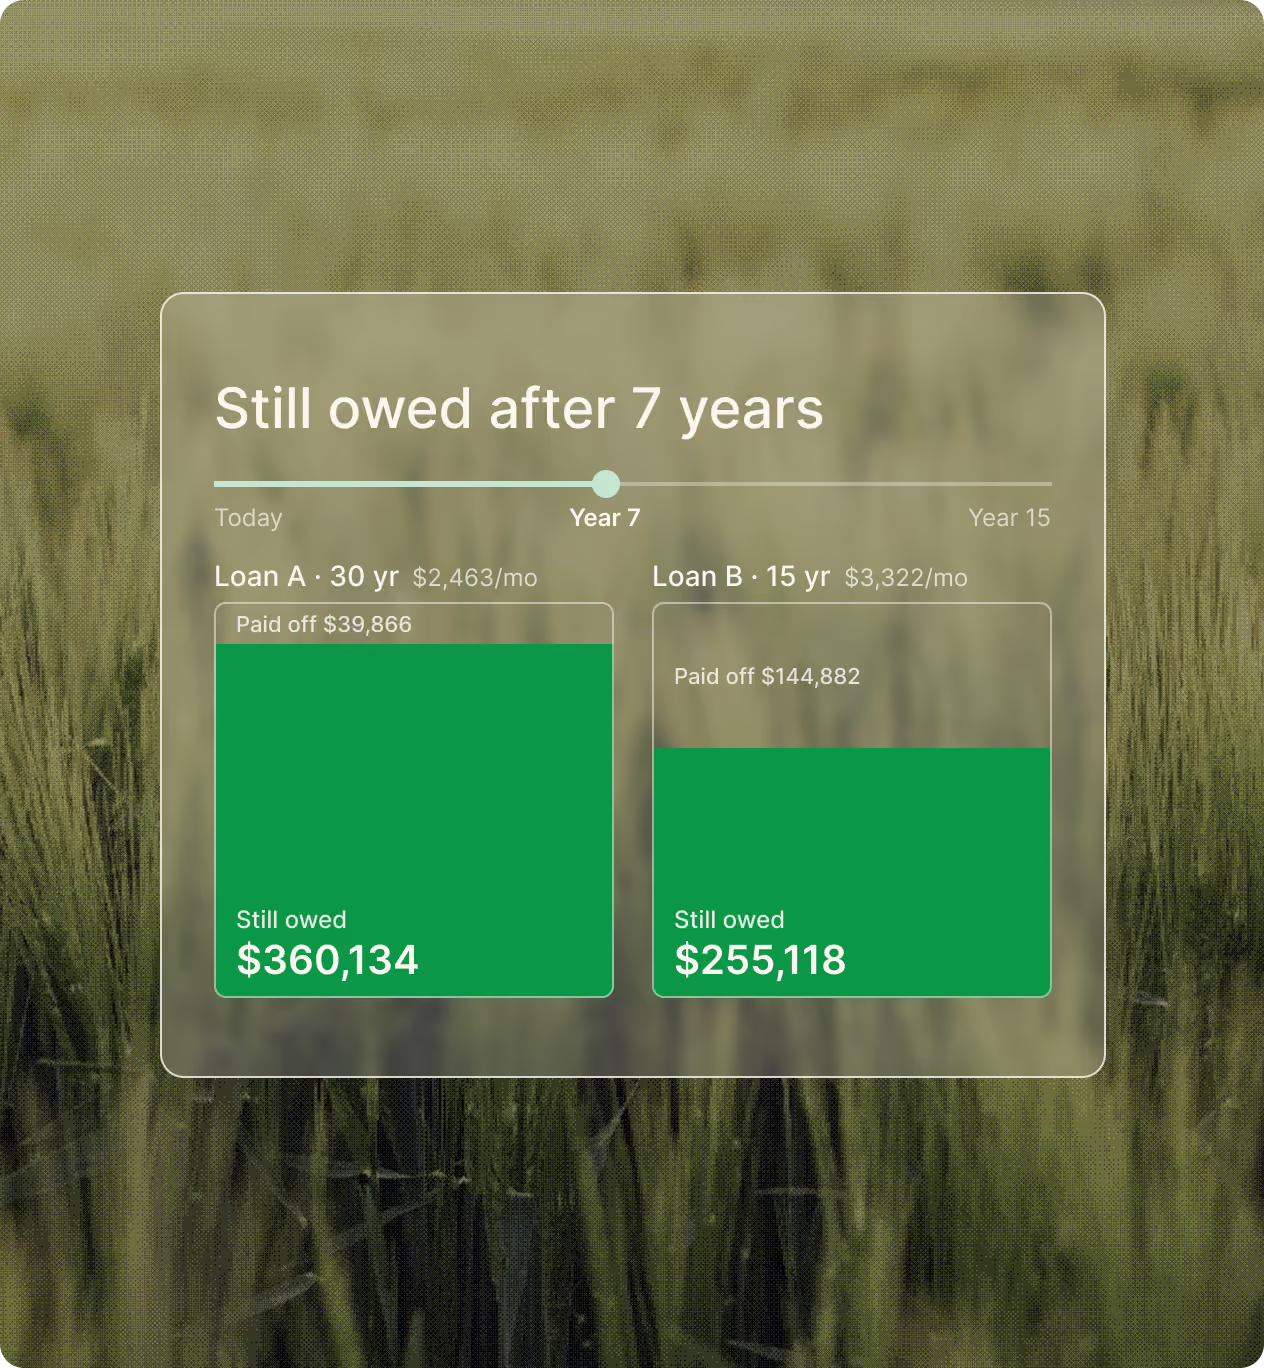
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about [name]
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
Generally, FHA financing is intended for owner-occupied primary residences, and borrowers are typically limited to one FHA-insured mortgage at a time. Certain exceptions may apply based on factors such as relocation, family size, or other qualifying circumstances.
It depends on your down payment. If you put down 10% or more, FHA mortgage insurance comes off after 11 years. If you put down less than 10%, you'd refinance into a conventional loan, or a VA loan if you're eligible, to remove it. Your loan officer can walk you through your options.
It depends on your income, debts, credit and where you're buying, since FHA loan limits vary by county. Our affordability calculator gives you a starting point, and your loan officer can give you a firm number.
Less than many conventional loans ask for. The exact amount depends on your credit and the home you choose, and all of it can come from gift money. Your loan officer can give you your number before you apply. Home sellers can also contribute up to 6% of your closing costs.
It's an FHA loan that rolls the cost of repairs or renovations into your mortgage, at purchase or when you refinance. Fairway offers a Limited 203(k) for smaller, non-structural projects and a Standard 203(k) for larger or structural work.
No. Repeat buyers can use FHA too, as long as the home will be your primary residence and you meet the guidelines.
Yes. Eligible homeowners may be able to refinance an FHA loan to lower their interest rate, reduce their monthly payment, change their loan term, or pursue other financial goals. Depending on your situation, options may include FHA Streamline Refinancing or refinancing into a conventional loan. With an FHA Streamline Refinance, your current loan must be FHA-insured and current, you can't take out more than $500 in cash, and the new loan must give you a net tangible benefit.
It depends on your credit and debts. If your credit score is lower or your debt is higher, an FHA loan might be the cheaper option over the life of the loan. With stronger credit, a conventional loan can come out ahead, even at the same interest rate. Your local Fairway loan officer can compare both for you.
Ready to see if an FHA mortgage fits?
It starts with a conversation. Tell us about your plans. Your local Fairway loan officer will reach out to walk you through what you'd put down and whether you qualify.