VA Home Loan Property Requirements: A-to-Z Guide
Lorem ipsum dolor sit amet, consectetur adipiscing elit
A VA home loan is a VA-backed home loan, guaranteed by the U.S. Department of Veterans Affairs. Because of that guarantee, there's often no down payment and no private mortgage insurance. Most borrowers pay a one-time VA funding fee instead, unless they're exempt. A down payment may still be needed if part of your benefit is tied up in another VA loan. VA loans depend on your entitlement and eligibility, qualifying factors such as income and credit guidelines, and property limits.

If you've served, VA home loans for veterans may already be within reach. Your loan officer can request your Certificate of Eligibility for you.
Looking to buy or moving for a new assignment? VA mortgages work for active-duty service members too, and you can use the benefit more than once.
Eligible surviving spouses can often use the same benefits of VA home loans.

A VA mortgage isn’t only for buying a move-in-ready home. It can also cover repairs, a new build or a refinance. Here’s where each one fits.
Articles & advice
Lorem ipsum dolor sit amet, consectetur adipiscing elit

Lorem ipsum dolor sit amet, consectetur adipiscing elit
See what a VA mortgage can do, and what it asks of you, before you talk numbers.
With full entitlement, you can often purchase or build a new home without a down payment.
VA loans don't carry private mortgage insurance, even without a down payment.
You can use your VA benefit more than once. Your loan officer can check your entitlement.
This certificate shows the VA that you qualify, based on your service. Your loan officer can request it for you.
VA loans are for your primary residence, including houses, townhomes and VA-approved condos.
You'll show reliable income and meet credit guidelines. Your loan officer can tell you where you stand before you apply.
Compare side by side
Which is the better fit depends on your eligibility, your savings, and your plans.
Often a fit if you have a larger down payment saved or aren't eligible for VA.
Down payment
Mortgage insurance
Who can use it
A VA purchase loan built for eligible veterans, service members, and surviving spouses.
Down payment
Mortgage insurance
Who can use it
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
No. VA loans don't have private mortgage insurance, even with no down payment. Most borrowers pay a one-time VA funding fee instead, unless they're exempt. You can pay the fee at closing or roll it into your loan, and the seller may agree to pay it. The fee is a percentage of your loan amount, based on your down payment and whether you've used a VA loan before.
It's the VA's record that you qualify for the benefit. It's based on your length of service or service commitment, your duty status and your character of service. It also shows whether you have full or partial entitlement. Your loan officer can request it when you're ready.
Entitlement is the amount the VA will guarantee on your loan. With full entitlement, you can often buy with no down payment. If part of it is tied up in another VA loan, you may need some money down.
Yes. You may be able to use your VA home loan benefit more than once, depending on your available entitlement and the status of any existing or previous VA loan. A loan officer can help review your eligibility and available options. If a previous VA loan isn't paid off, you may have only partial entitlement or none left. Paying off that loan restores your full entitlement.
Yes, borrowers can use a VA construction loan to finance the construction of a new primary residence along with the land. You can also use a VA loan to buy land that already has a home on it. The VA doesn't limit how much land you buy, but similar properties nearby must be residential. For example, a 10-acre lot among income-producing farms may not qualify, while one among similar hobby farms is more likely to.
The VA doesn't set a minimum score, but lenders do, and Fairway has its own guidelines. Your loan officer can tell you where you stand before you apply.
Yes. VA loans cover a range of homes, including townhomes and VA-approved condos, as long as the home will be your primary residence.
Only some of them. The VA funding fee can be rolled into your loan amount. Other closing costs can't be, but you and your agent may be able to negotiate seller or lender concessions to lower what you pay up front. Your local Fairway loan officer can walk you through the numbers.
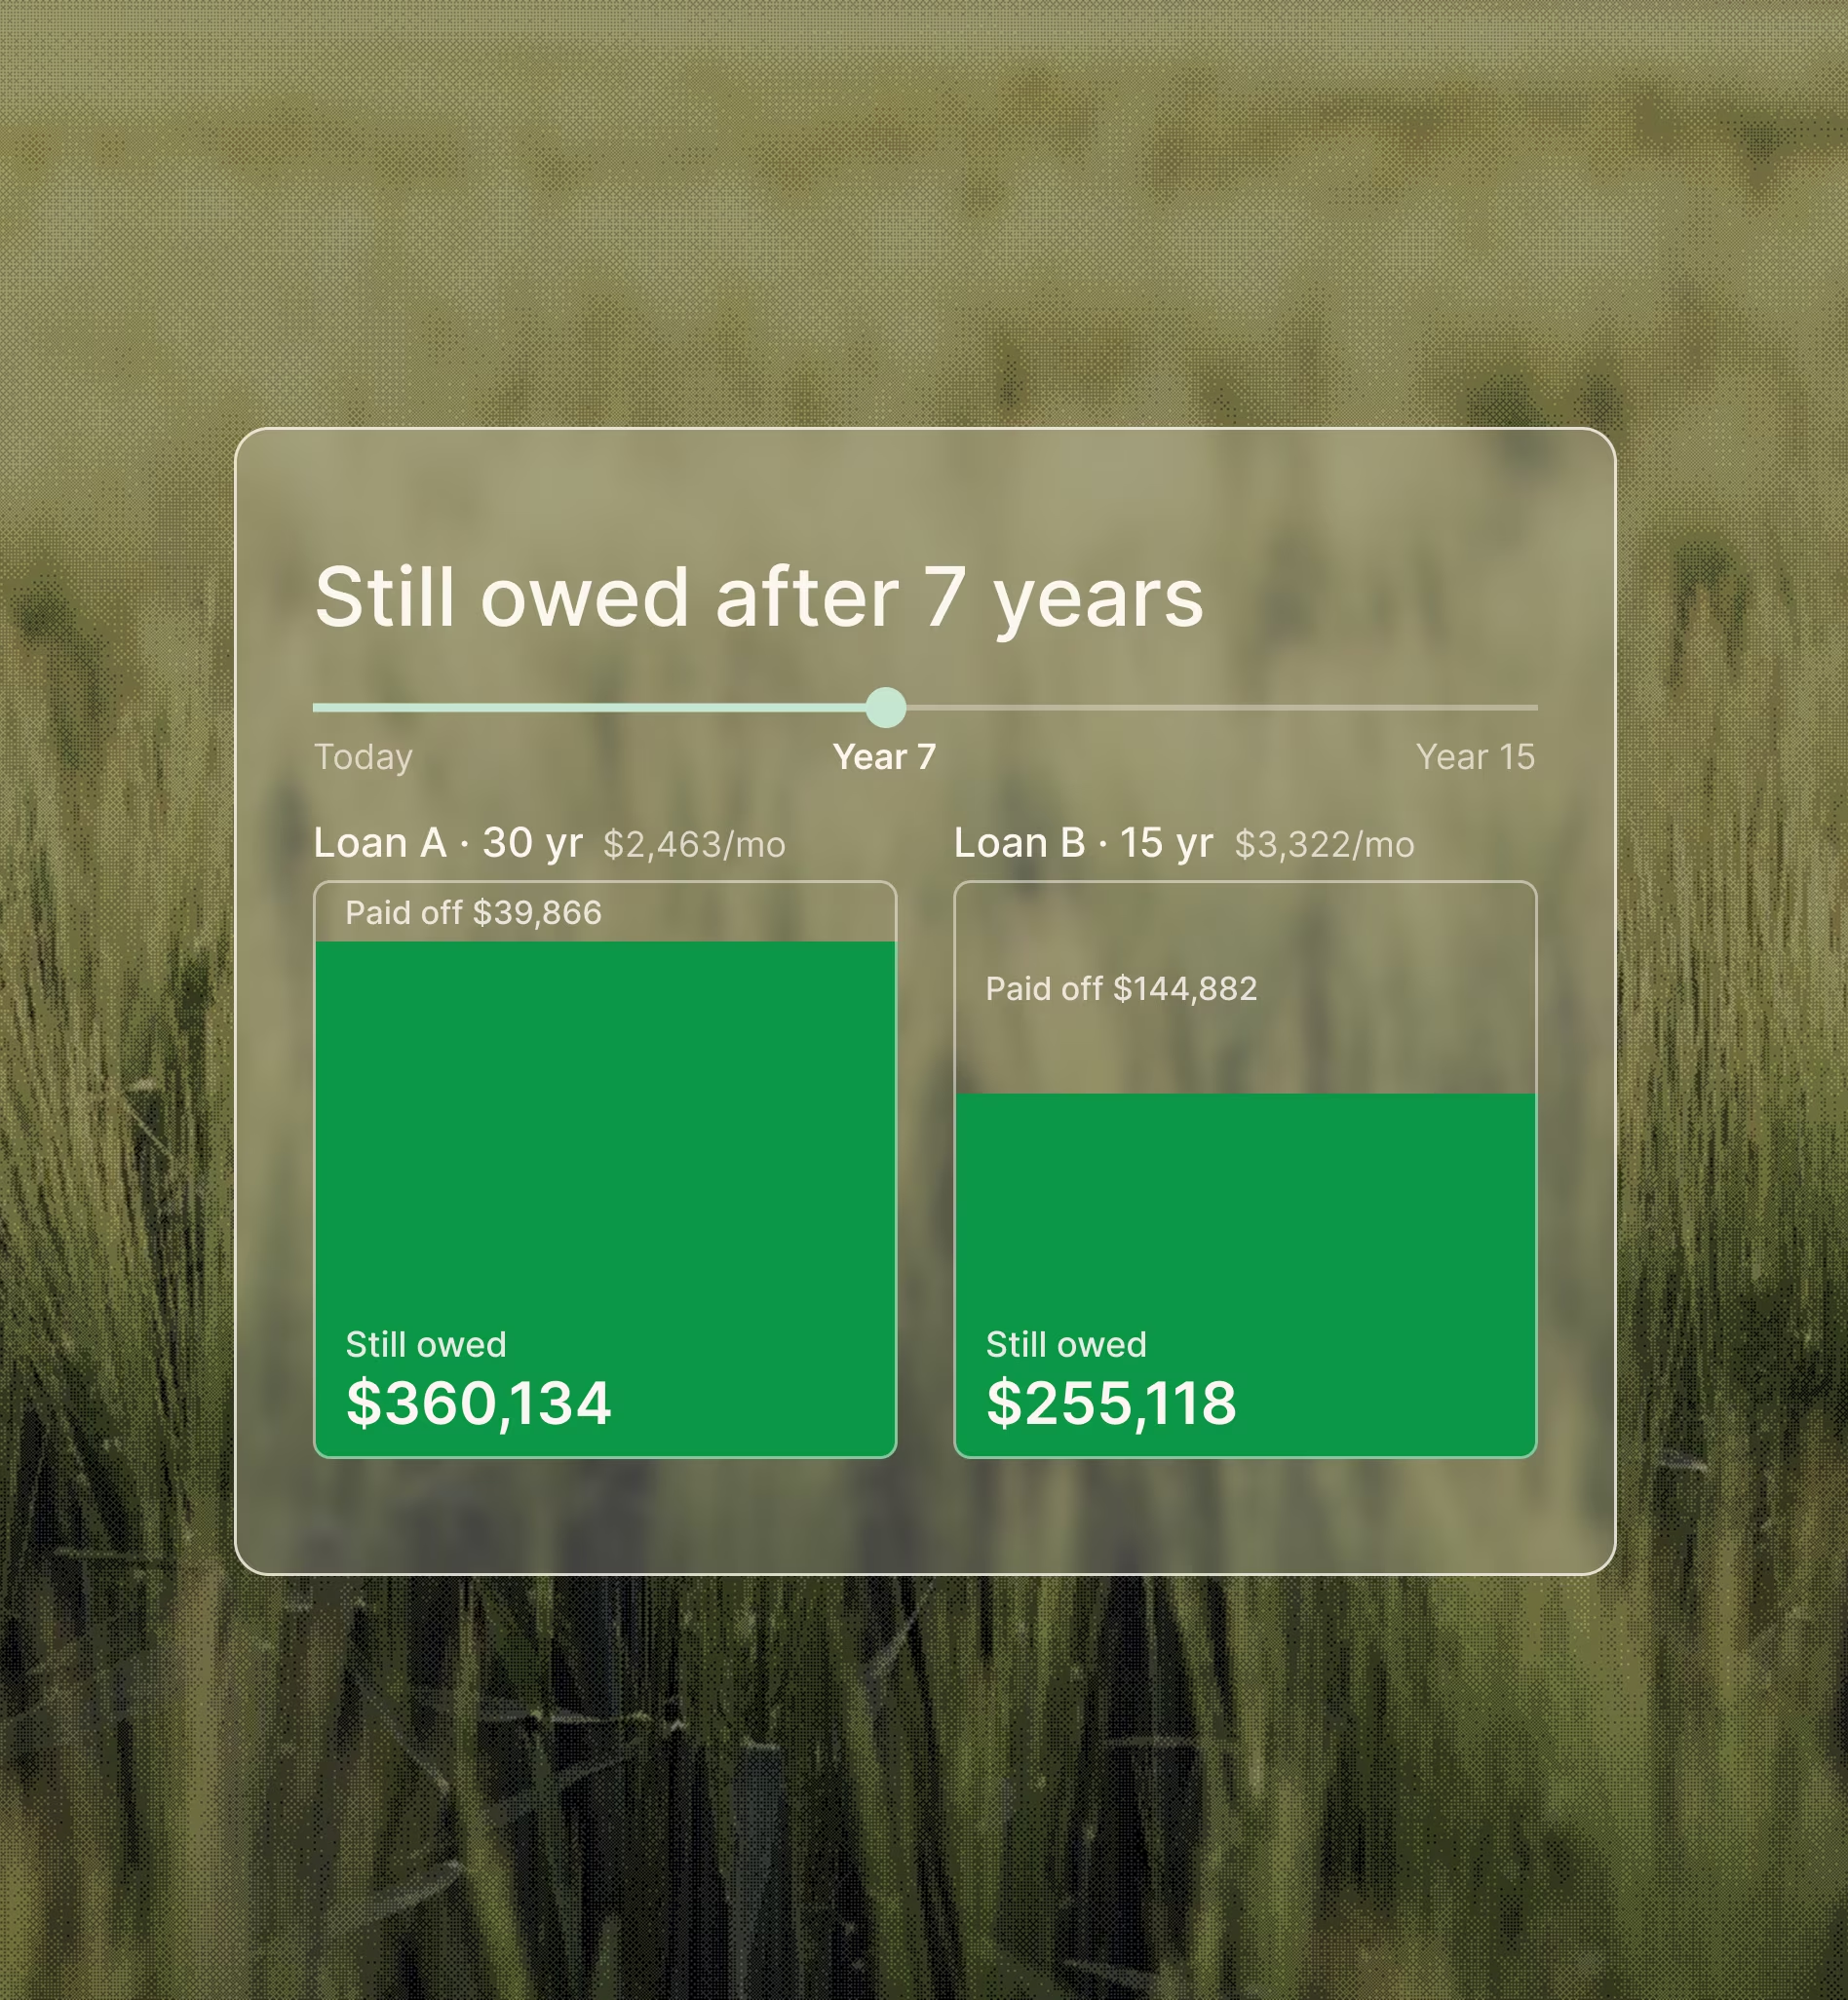
Yes. A fixed-rate VA loan comes with a 30- or 15-year term. The 15-year option has higher monthly payments, but you build equity faster. If you're serving and may relocate in the next few years, a VA adjustable-rate mortgage may fit better. Your loan officer can compare both for your plans.
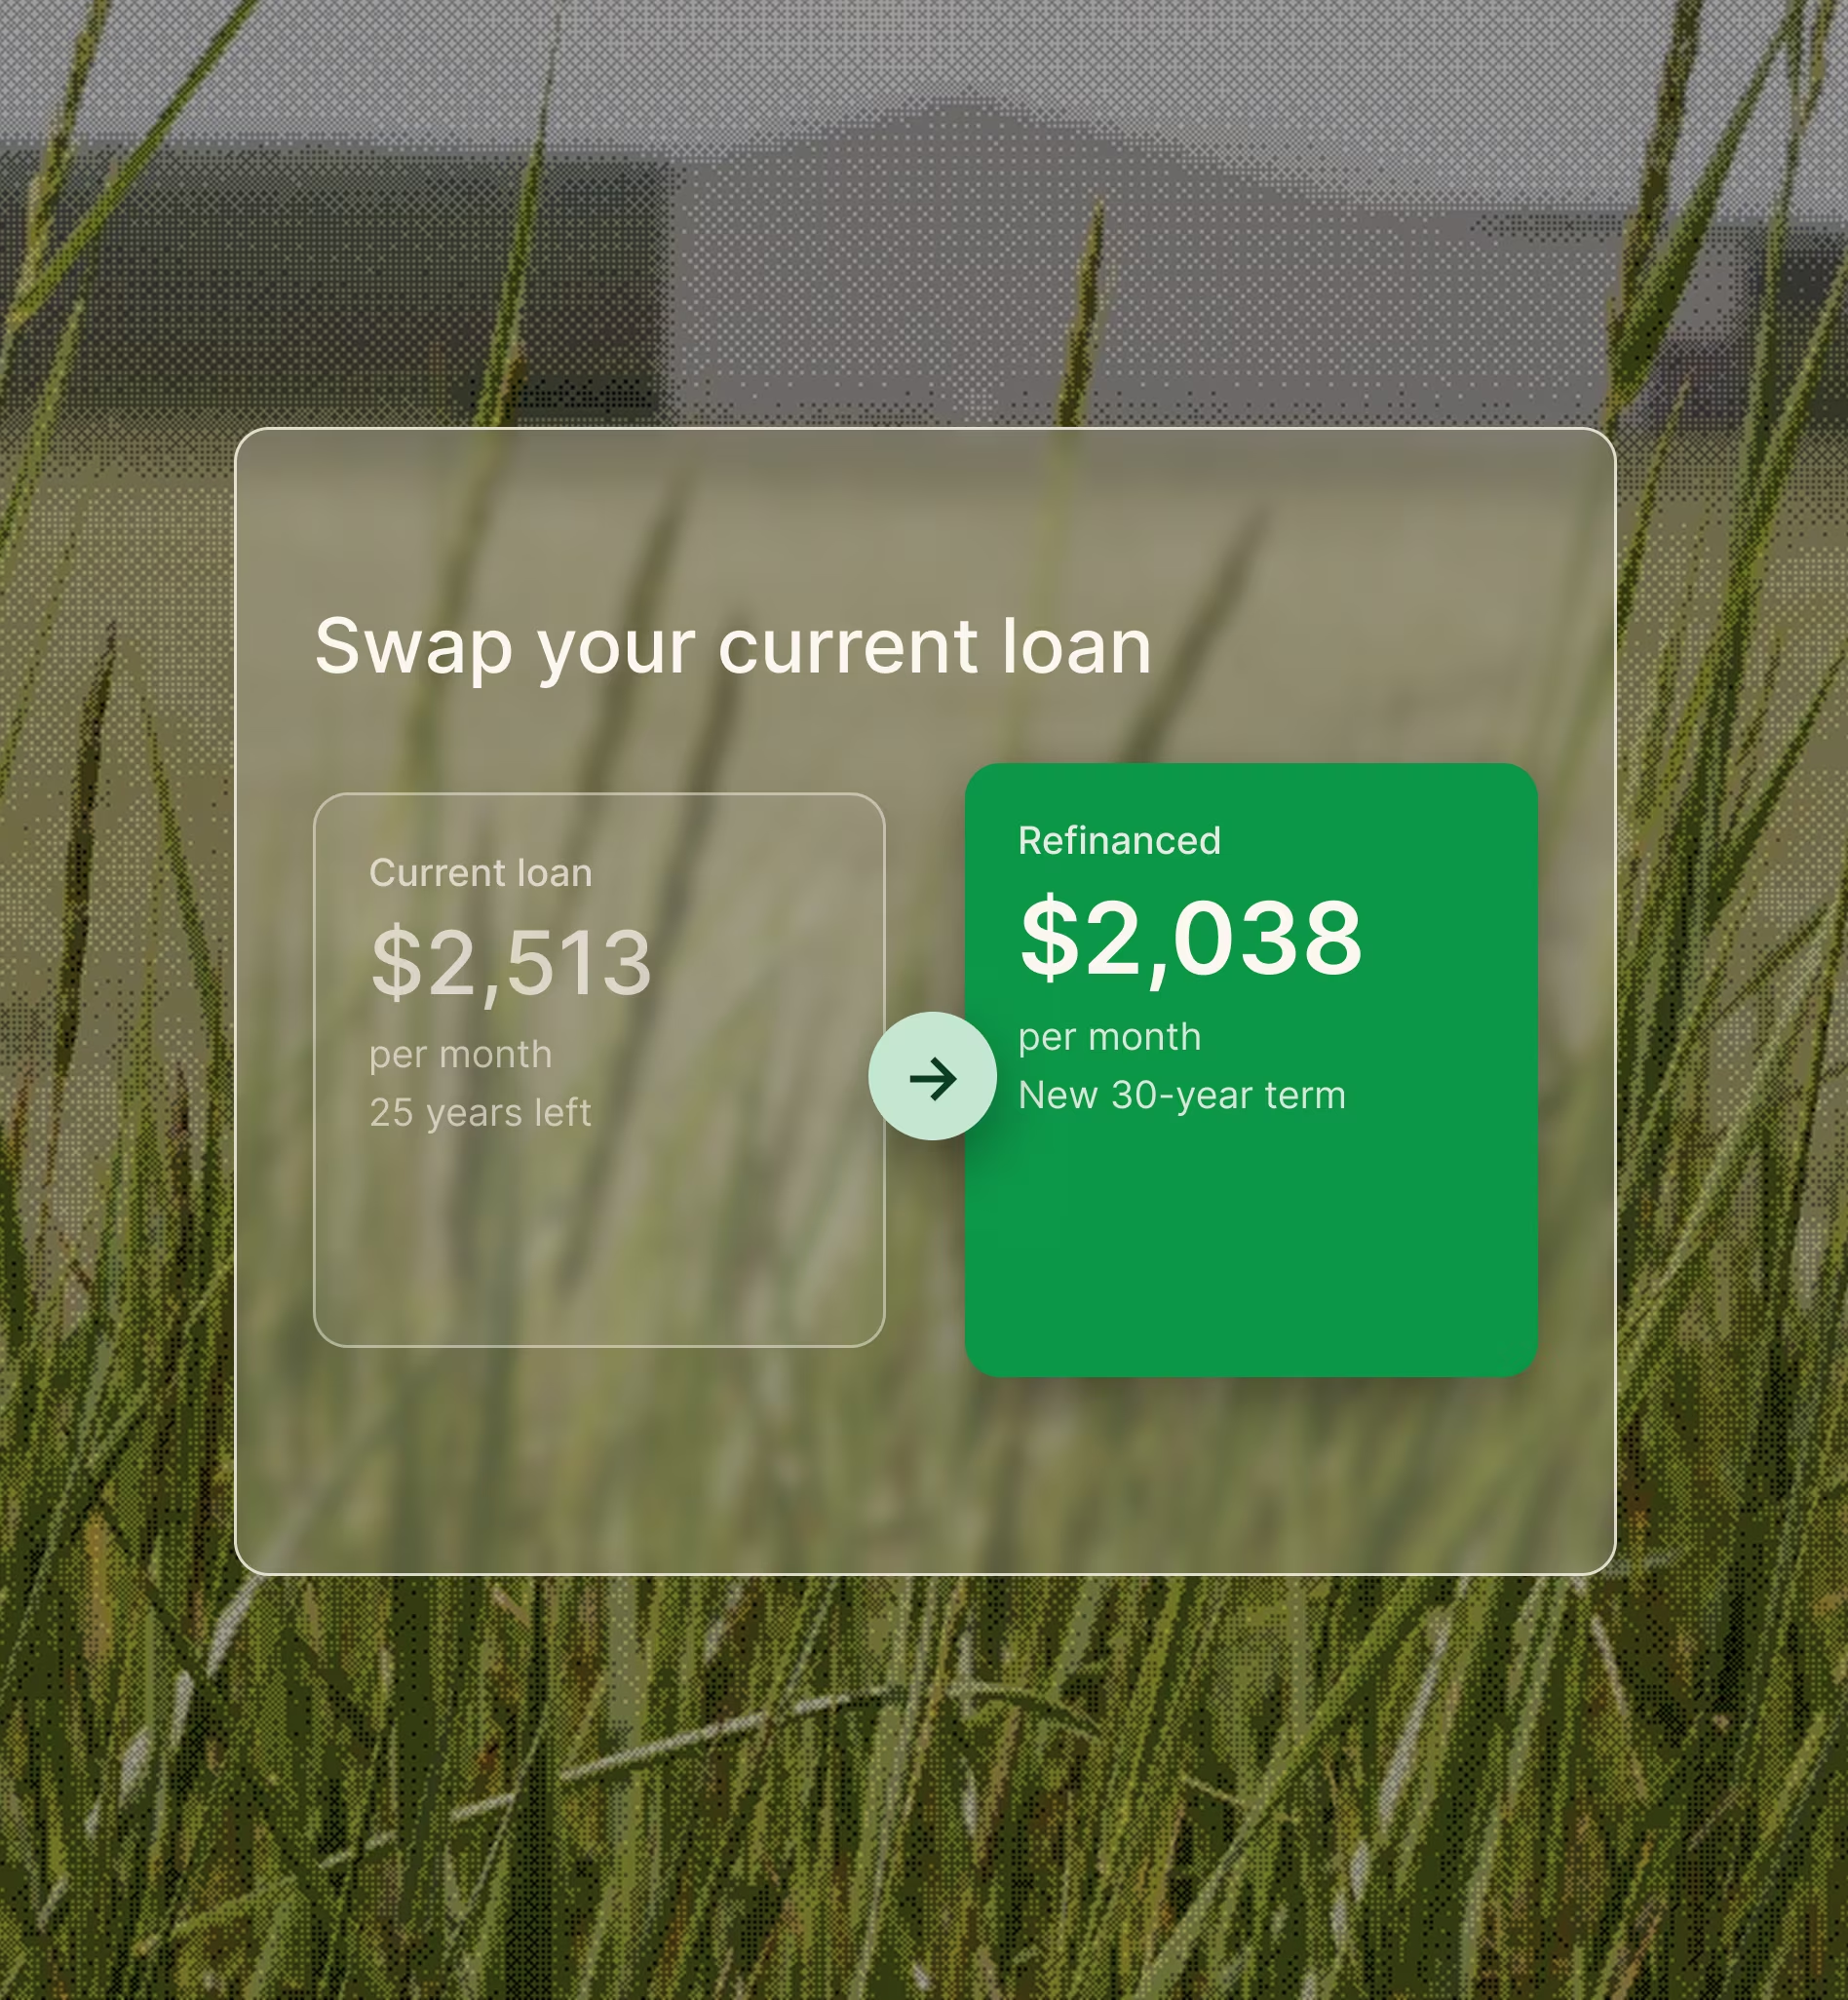
Yes. A VA cash-out refinance can replace a VA loan or a non-VA loan, and you can use the cash for things like tuition, paying off debt or home improvements. If you already have a VA loan, an Interest Rate Reduction Refinance Loan (IRRRL) is the streamlined option. It can move an adjustable rate to a fixed rate, but it doesn't pay out cash.
It starts with a conversation. Tell us about your service and your plans. Your local Fairway loan officer will reach out, request your Certificate of Eligibility and walk you through what you'd put down.