What is a USDA mortgage?
USDA home financing, often called a USDA Rural Development loan, offers mortgage options guaranteed by the U.S. Department of Agriculture to help eligible families purchase homes in designated rural areas, small towns, and suburbs. These fixed-rate loans finance up to the home’s full appraised value. Rather than traditional mortgage insurance, borrowers pay a guarantee fee, with a portion paid at closing and an ongoing annual fee typically included in the monthly payment.

Who are USDA home loans for?
Families buying outside a big city
Many suburbs and small towns qualify, not just farmland. Your loan officer can check any address against the USDA map.
Low- to moderate-income households
USDA loan income limits vary by location, so you may qualify in one area even if your household income exceeds the limit in another.
Buyers without the savings for a down payment
With no down payment required for eligible borrowers, you can keep more of your savings for moving expenses, repairs, and making your new home your own. Eligible gift funds may also help cover closing costs.

More USDA financing options
A USDA loan can also help after you buy, or with a home that needs work. Here’s where each one fits.


USDA mortgage benefits and requirements
See what a USDA mortgage can do, and what it asks of you, before you talk numbers.
No down payment
If you qualify, a USDA loan can cover the home’s full appraised value, so you don’t need a down payment.
One steady loan
Every USDA loan is a 30-year loan with a fixed rate, so you can easily budget your monthly payment.
More room on credit
USDA credit guidelines are more flexible than many conventional loans. Your loan officer can tell you where you stand.
A home in an eligible area
The home must be in a USDA-eligible rural or suburban area. Your loan officer can check any address against the USDA map.
Household income within the county limit
USDA sets income limits by county and household size. Your loan officer will check your household’s income against the limit where you’re buying.
A home you’ll live in
USDA loans are for your primary residence, and you’ll meet USDA’s residency and credit guidelines.
Compare side by side
USDA vs conventional
Which is the better fit depends on your eligibility, your savings, and your plans.
Conventional loans
Often a fit if you have some savings and want to buy anywhere.
Down payment
- Usually some money down
Where you can buy
- Anywhere
Income limits
- None
USDA loans
Built for buyers in eligible rural and suburban areas.
Down payment
- None if you qualify
Where you can buy
- Eligible rural and suburban areas
Income limits
- Set by county and household size
Tools & Calculators
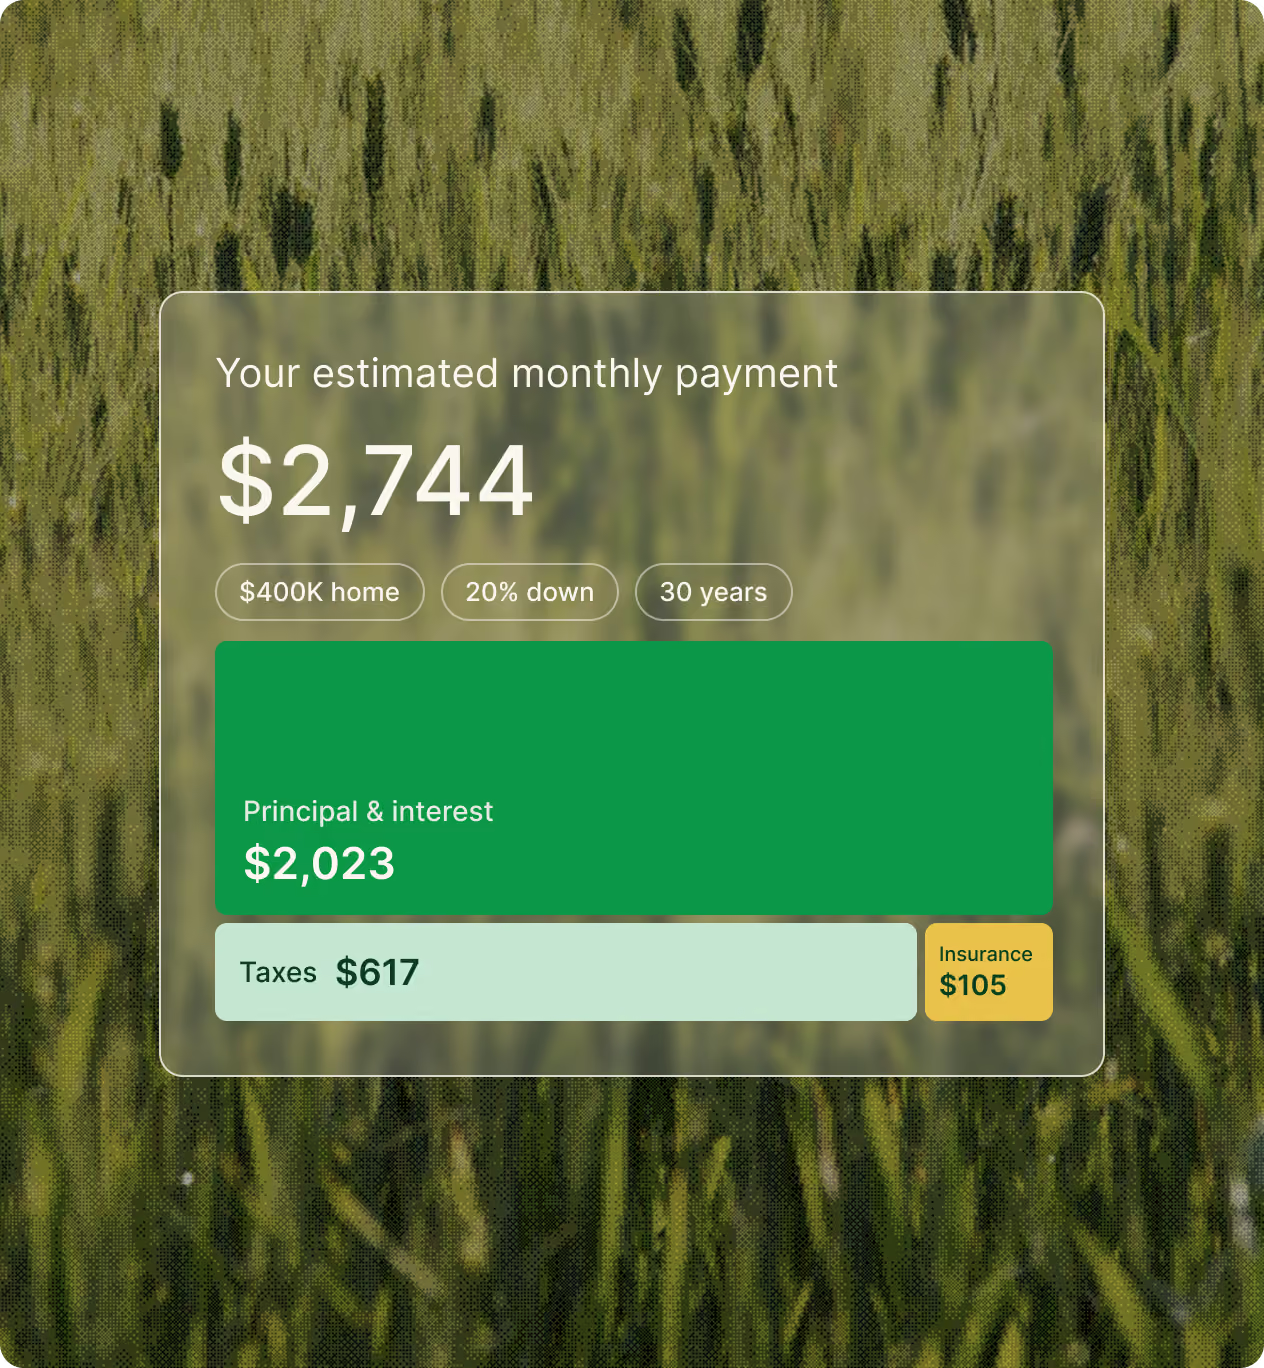
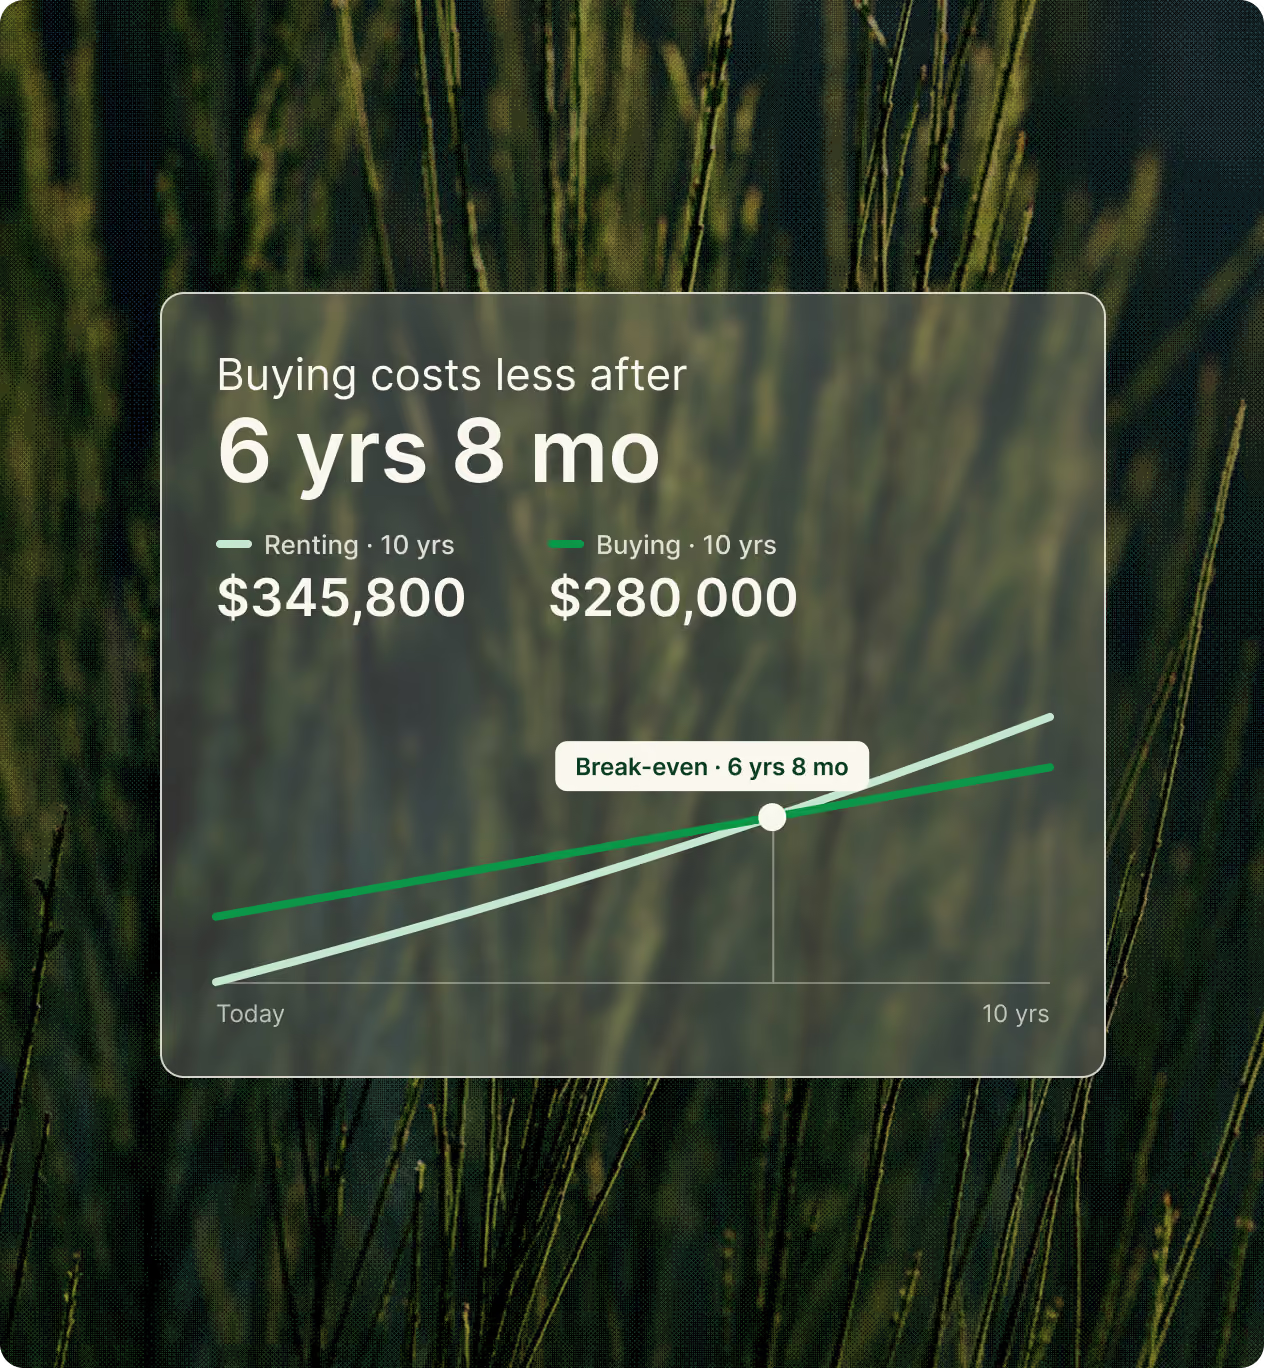
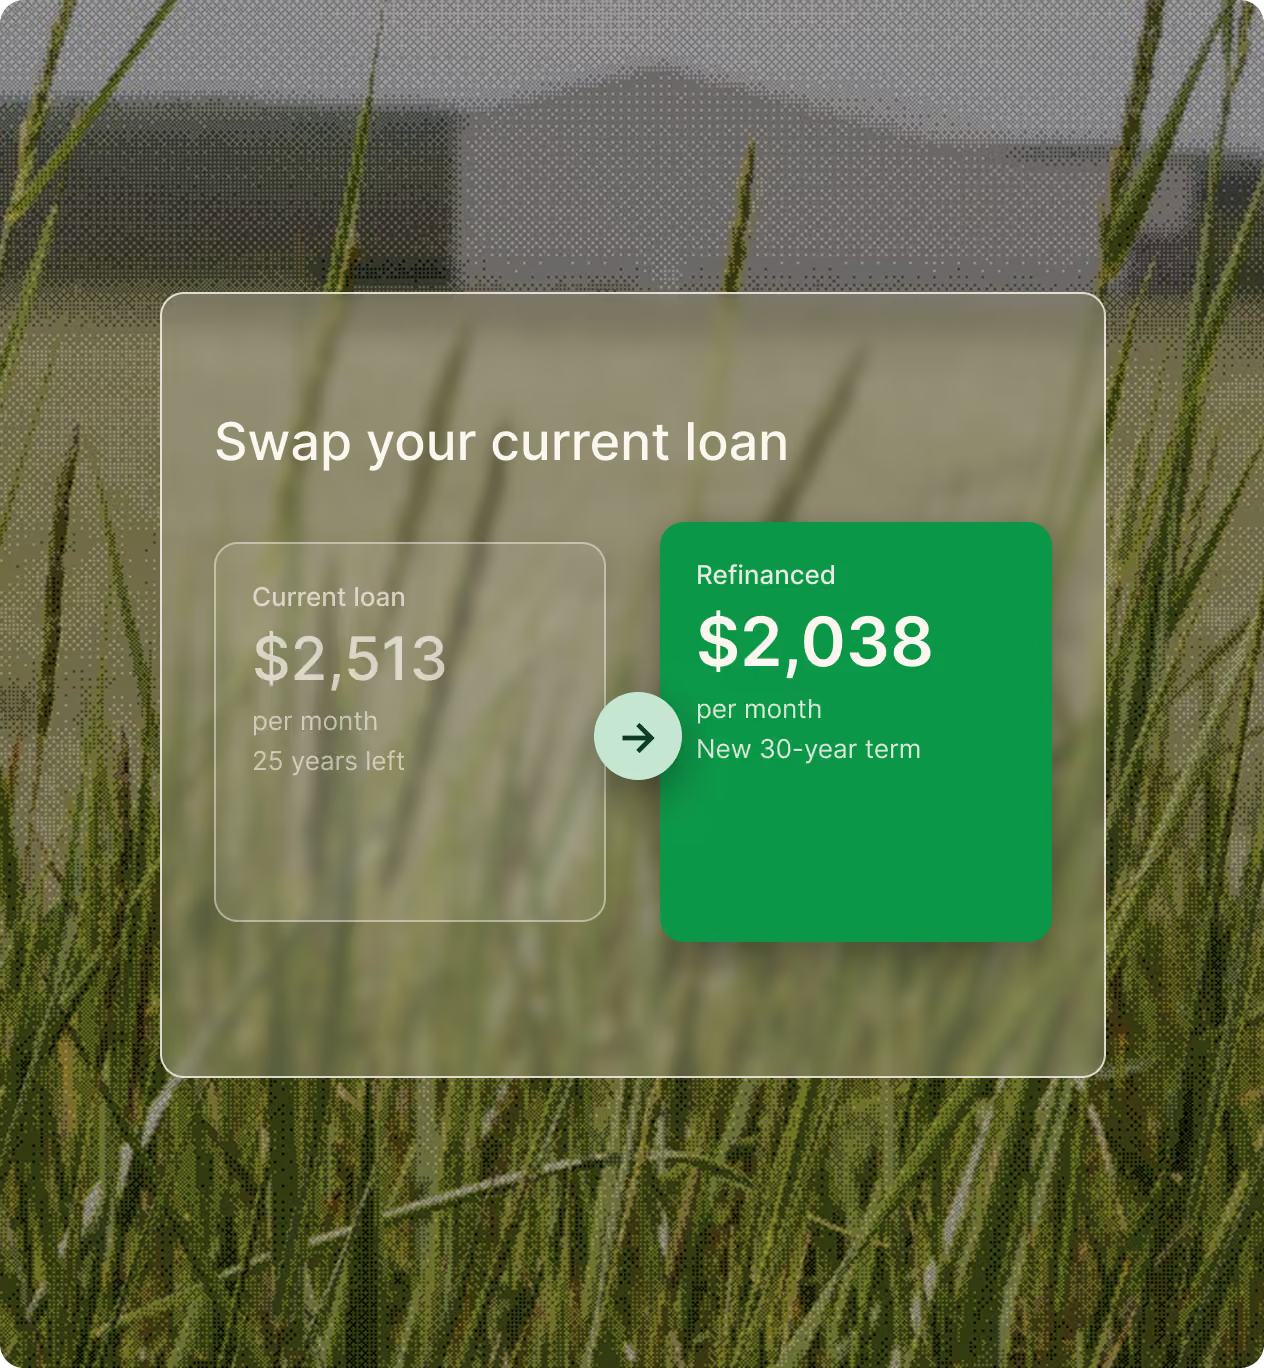
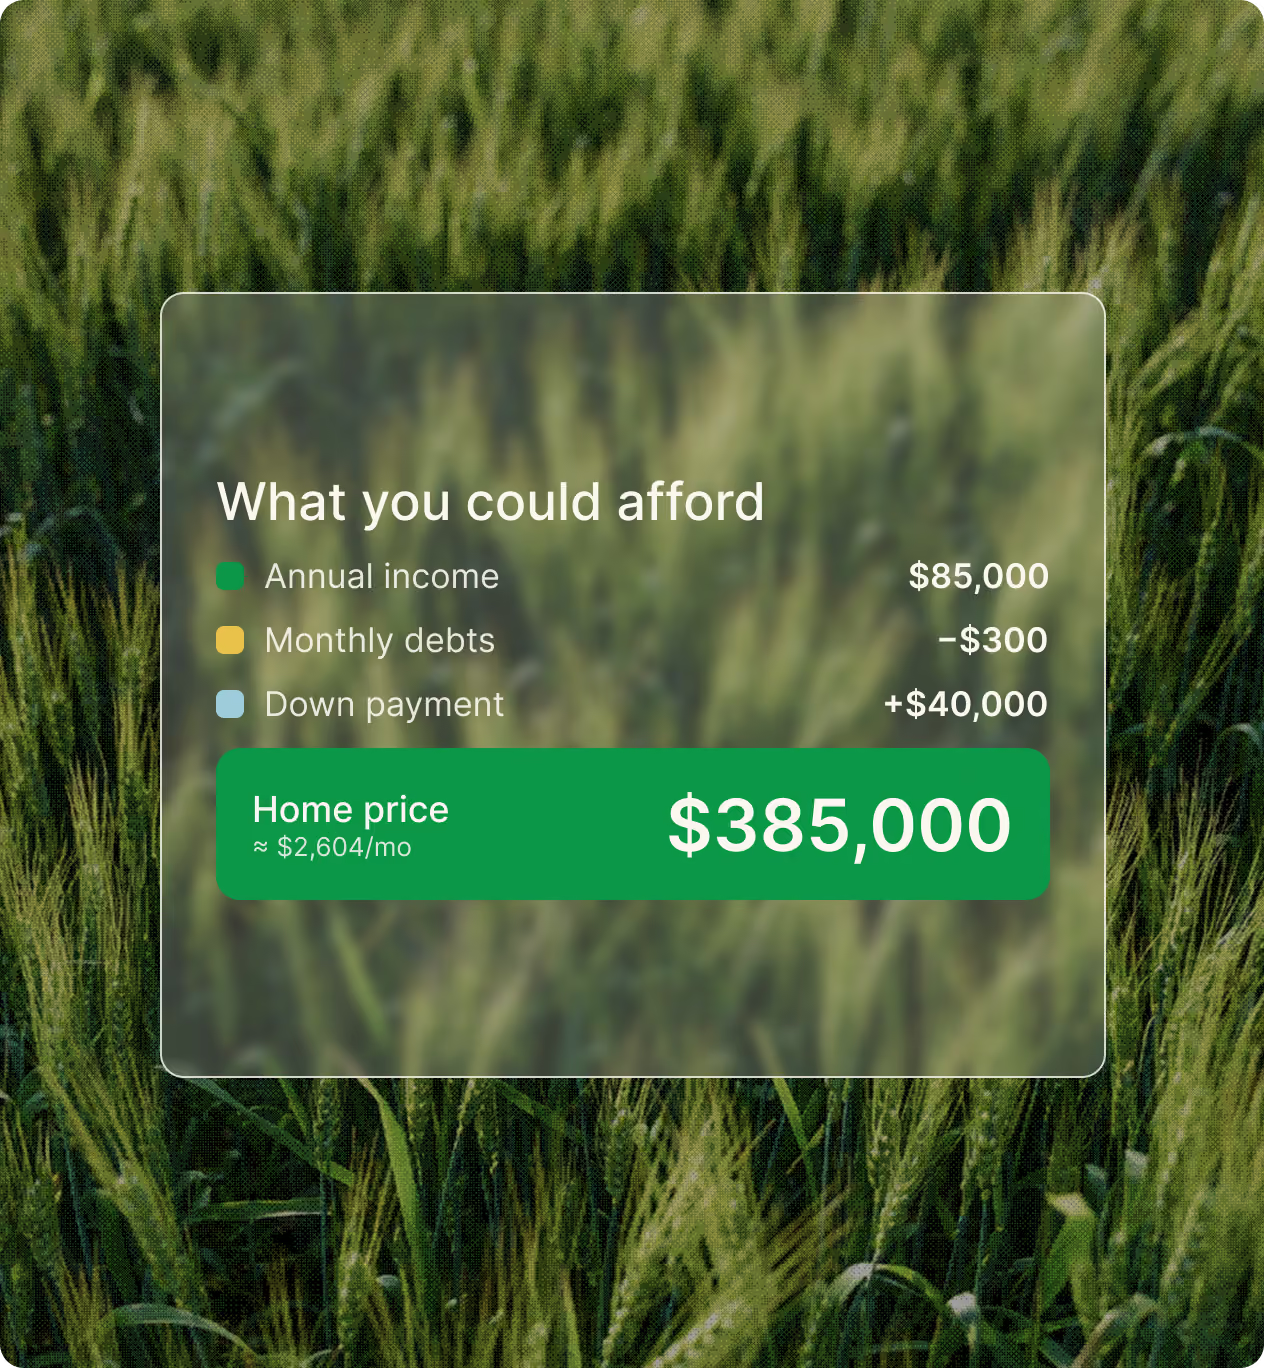
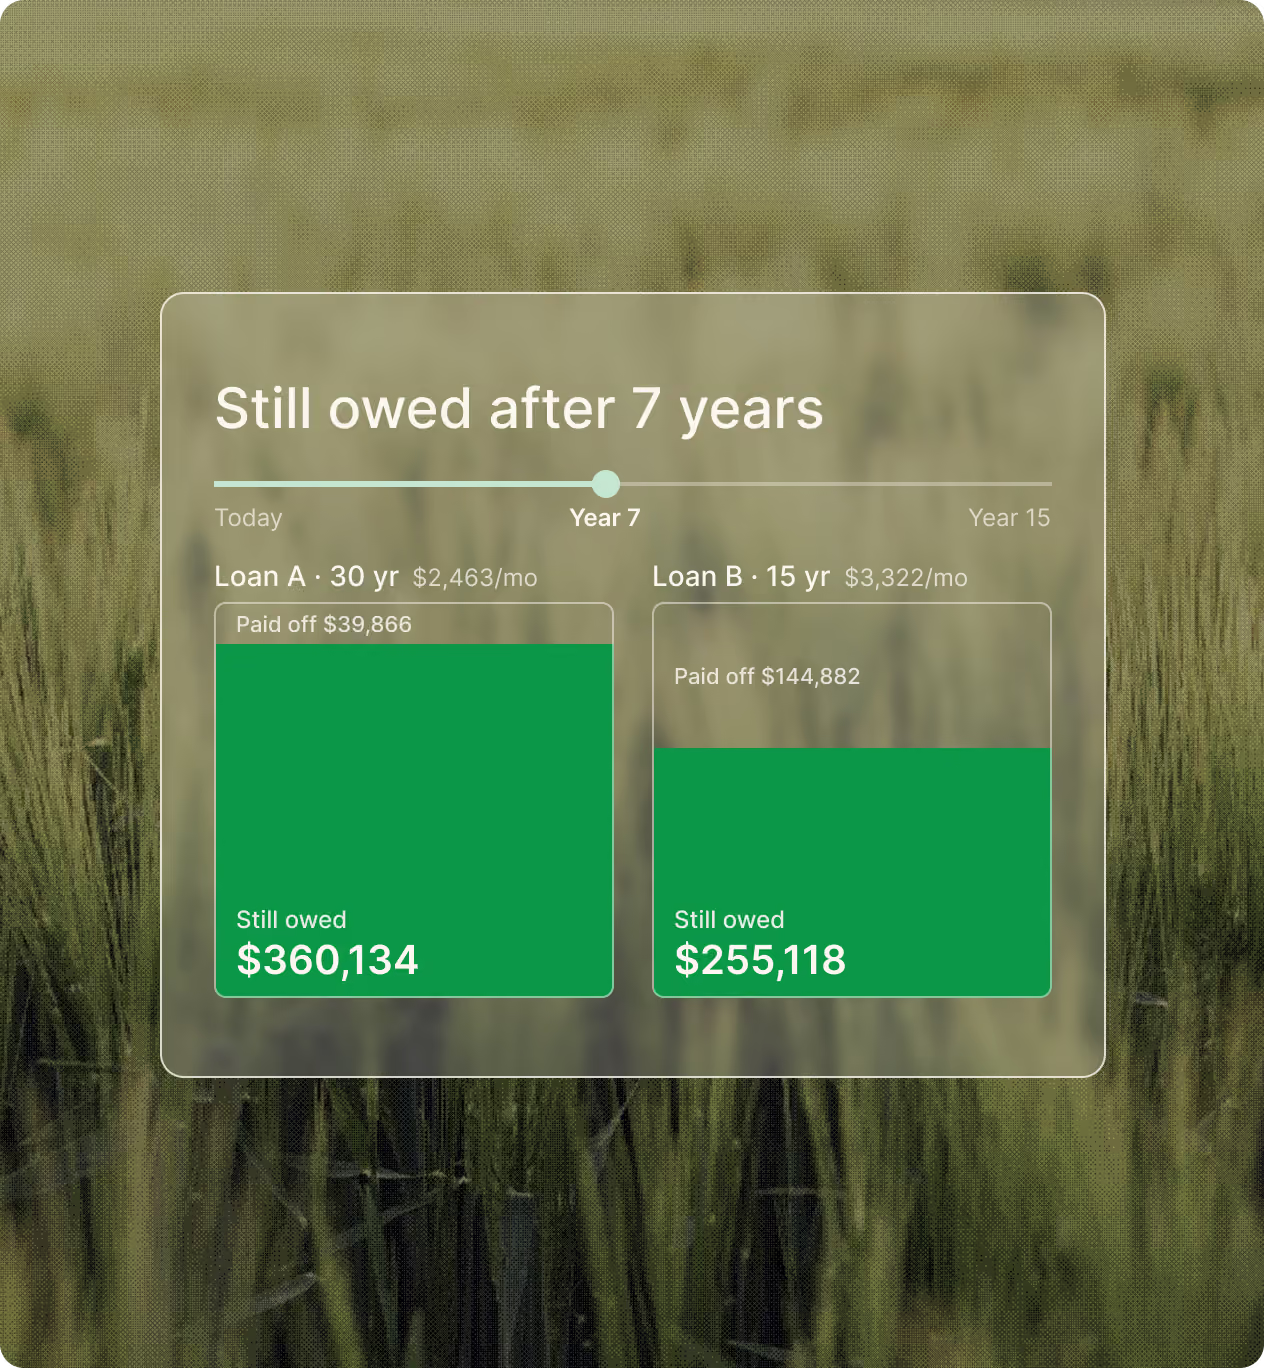
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about [name]
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
The home must be in a USDA-eligible area, be your primary residence, and meet USDA’s property standards. Your loan officer can check an address before you make an offer.
Households with income at or under the USDA limit for their county, buying a home they’ll live in, who meet USDA’s residency and credit guidelines.
Not mortgage insurance, but USDA loans carry a guarantee fee that does a similar job. Part is paid at closing and part monthly. You can finance the upfront part into your loan. And typically, the lower your credit score, the more the USDA guarantee fee works in your favor compared with a conventional loan's PMI.
Yes. A USDA Streamline Refinance can replace an existing USDA loan with less paperwork, and you can refinance into another loan type if you qualify. If you're refinancing from one USDA loan into another, you may be able to skip the credit and income approval step.
USDA keeps a map of eligible areas, and many suburbs and small towns qualify, not just farmland. Your loan officer can check any address for you.
It depends on your county and household size. USDA sets the limits by area, so a family over the limit in one county may qualify in another.
Not if you qualify. A USDA loan can cover the full appraised value of the home, and gift funds can help with what’s due at closing.
Ready to see if a USDA mortgage fits?
It starts with a conversation. Tell us where you want to buy. Your local Fairway loan officer will reach out and check the address and your household income against USDA’s limits.